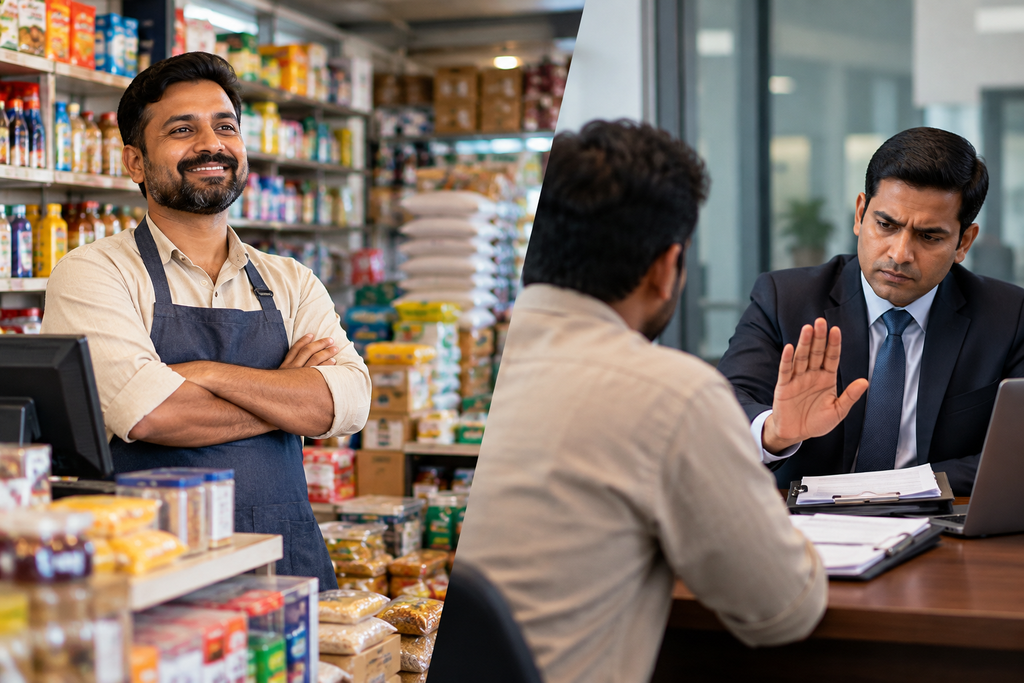
Walk into any busy hardware store, textile distributor, or regional FMCG stockist on a Tuesday afternoon, and you will likely see a healthy business. The counter is crowded, inventory is moving fast, and the daily cash drawer is full.
But if that same business owner walks into a bank manager’s office to request a ₹15 Lakh working capital loan to open a second branch, they often hit a brick wall.
The bank does not look at the foot traffic. Banks may ask for past ITRs, GST records and financial statements. For millions of unorganized small and medium-sized enterprises (MSMEs) in India, these documents simply do not exist because the business has operated entirely on rough notebooks and cash ledgers.
The rejection follows shortly after. However, getting denied credit is rarely a permanent dead end. It is usually just a symptom of a localized structural problem: the gap between the physical reality of your shop floor and the documented reality of your financial books. Bridging this gap does not require an MBA; it requires a systematic shift in how you record sales and present your margins.
The Problem with “Invisible” Revenue
When a business operates without formal invoicing, its revenue becomes invisible to institutional lenders. Banks operate on a strict matrix of risk assessment. They need to mathematically verify that your business generates enough surplus cash every month to cover a loan EMI without starving the core operations.
If you cannot produce historical data, you have to rely on projected financials. This means building a realistic Trading and Profit & Loss (P&L) account from scratch, usually by reverse-engineering your bank deposit history.
Credit managers look closely at two specific metrics during this process. First, the Gross Profit, which proves your basic trading margin on the goods you sell. Second, the Net Profit, which proves your absolute bottom line. If a business owner tries to do this manually without understanding the acceptable industry ratios, this can raise concerns during underwriting.
Before approaching a bank, business owners must understand how to mathematically prove their EMI capacity. This involves calculating your margin of safety and structuring projected financials without past ITRs, a step that requires mapping out your current physical assets and establishing a clean, legally sound opening capital defense.
Moving from Paper to Digital Compliance
The hardest part of formalizing a business is breaking the habit of the paper ledger. Informal notebooks alone may not provide the structured, verifiable records typically expected during tax scrutiny or credit assessment.
To build the kind of financial footprint that banks trust, the daily transaction data needs to be structured. You need to prove exactly what is leaving your warehouse and exactly what is coming into your bank account, matched against specific dates and customer profiles.
This is where moving away from manual billing methods becomes a non-negotiable step for growth. Using billing software for small businesses can help digitize invoices, track sales, maintain inventory records, and organize transaction data in one place. When every sale, no matter how small, is recorded through a centralized system, you stop guessing your monthly turnover and start tracking it with much greater accuracy.
The Section 44AD Advantage for MSMEs
One of the biggest fears unorganized retailers have about formalizing their books is the perceived burden of compliance. There is a common misconception that getting into the banking system requires hiring full-time accountants to maintain complex daily ledgers and calculate convoluted asset depreciation.
For many eligible small businesses, the Indian government actually provides a much simpler alternative. Under Section 44AD of the Income Tax Act (the Presumptive Taxation scheme), eligible businesses with a turnover of up to ₹2 crore can opt for presumptive taxation. The threshold increases to ₹3 crore when cash receipts do not exceed 5% of total turnover or gross receipts.
Instead, you can compute presumptive taxable income by applying a flat 8% rate to your cash receipts, and a reduced 6% rate to your qualifying digital receipts.
This can simplify tax compliance for eligible businesses, while accurate turnover and transaction records can also make it easier to present consistent financial information to lenders. The catch is that you still need a bulletproof mechanism to track that gross turnover figure accurately.
Creating a Verifiable Audit Trail
Banks love predictability. When you apply for a term loan or an overdraft facility, the credit manager will cross-reference your stated turnover with your GST returns and your bank statements. If there is a mismatch between the inventory you claim to have and the invoices you have generated, significant inconsistencies can delay or weaken the application.
Building this audit trail does not have to be an expensive, enterprise-level operation. For local shops and distributors, implementing specialized billing software for retail shop solves the problem at the point of sale. When your invoicing, inventory depletion, and basic accounting are tied together automatically, your business generates a verifiable data trail every time a customer checks out.
If you are running a retail operation today with aspirations of securing bank funding tomorrow, the transition needs to start at your billing counter. The businesses that secure the best interest rates and the highest credit limits are not necessarily the ones making the most money, they are the ones that can prove their margins on paper.
Author Bio – Avijit Mukherjee is a practicing Advocate and Tax Consultant leading Mookherjee Associates in Kolkata. Specializing in MSME compliance, corporate taxation, and credit structuring, he helps independent retailers and businesses transition into formal financial ecosystems to secure growth capital. He holds a US-CMA and regularly represents clients in tax litigation and financial assessments.
