
GST e-Invoice: Meaning, Applicability, Rules, Format & Generation Guide
Understand the latest GST e-Invoice rules, ₹5 crore applicability threshold, exemptions, format, IRN, QR code, reporting timelines and generation process for Indian businesses.
What Is an e-Invoice?
A GST e-Invoice is a B2B, export, credit note or debit note reported by an eligible taxpayer to an Invoice Registration Portal (IRP), where it is validated and assigned an Invoice Reference Number (IRN) and signed QR code. In India, e-Invoicing is currently mandatory for notified taxpayers with aggregate annual turnover of ₹5 crore or more, subject to exemptions.
An e-Invoice is not created by the GST portal itself. A business first creates the invoice in its ERP, accounting or billing software and then reports the prescribed invoice data to an IRP for validation.
GST e-Invoice Rules at a Glance
| Question | Current rule |
|---|---|
| Who must generate e-Invoices? | Notified GST-registered taxpayers whose aggregate annual turnover exceeded ₹5 crore in any financial year from 2017-18 onwards, unless exempt. |
| What transactions are mainly covered? | B2B invoices, export invoices, debit notes and credit notes covered by the e-Invoice mandate. |
| Are B2C invoices covered? | No. B2C invoices are not reported to the IRP under the current e-Invoice mandate. |
| Is a Bill of Supply covered? | No. A Bill of Supply is not reported for e-Invoicing. |
| What does the IRP return? | An IRN, acknowledgement details and a digitally signed QR code after validation. |
| What is the 30-day reporting rule? | From 1 April 2025, taxpayers with AATO of ₹10 crore or more must report applicable invoices, debit notes and credit notes within 30 days of the document date. |
How Does the GST e-Invoice System Work?
- Create the invoice: The supplier prepares the invoice in billing, accounting or ERP software.
- Prepare the required data: Mandatory invoice fields are converted into the prescribed e-Invoice schema/JSON format.
- Report to an IRP: The invoice data is uploaded or transmitted to an authorised Invoice Registration Portal.
- IRP validation: The system checks the invoice data and validates required fields.
- IRN and QR code: After successful validation, the IRP generates the IRN and returns a digitally signed QR code.
- Use the registered invoice: The supplier issues the invoice with the required e-Invoice details. Relevant data can also flow to connected GST and e-Way Bill processes.
Businesses that use integrated software can complete much of this workflow without manually re-entering invoice data. See how the myBillBook e-Invoicing feature supports the invoicing workflow.
e-Invoice Applicability: Who Must Generate e-Invoices?
GST e-Invoicing is mandatory for notified registered taxpayers whose aggregate annual turnover exceeded ₹5 crore in any financial year from 2017-18 onwards, subject to the exemptions notified under GST law.
Which financial year’s turnover is considered?
Applicability is checked using aggregate annual turnover from any preceding financial year beginning with FY 2017-18. Once a taxpayer falls within the notified mandate based on a relevant preceding year, the business should continue to follow the applicable e-Invoicing rules unless an exemption applies.
How can a business check e-Invoice applicability?
Check the GSTIN and turnover history against the current notified threshold and exemptions. The GST e-Invoice ecosystem also provides enablement/applicability checking tools. A business should not rely only on whether a GSTIN appears enabled on a portal; legal applicability depends on the notified rules.
e-Invoice Turnover Limit and Applicability Timeline
| Notification | Turnover threshold | Effective date |
|---|---|---|
| 61/2020 | Above ₹500 crore | 1 October 2020 |
| 88/2020 | Above ₹100 crore | 1 January 2021 |
| 05/2021 | Above ₹50 crore | 1 April 2021 |
| 01/2022 | Above ₹20 crore | 1 April 2022 |
| 17/2022 | Above ₹10 crore | 1 October 2022 |
| 10/2023 | Above ₹5 crore | 1 August 2023 |
The current notified threshold is ₹5 crore. Businesses should avoid assuming a future reduction until it is officially notified.
Who Is Exempt from GST e-Invoicing?
Certain notified classes of registered persons remain exempt from e-Invoicing even where turnover crosses the prescribed threshold. These include specified entities such as insurers, banking companies and certain financial institutions, goods transport agencies, suppliers of passenger transportation services, suppliers of admission to exhibition of cinematograph films in multiplex screens, and SEZ units, subject to the exact wording of the applicable notification.
SEZ unit vs SEZ developer: The exemption applies specifically to SEZ units under the notified provision; businesses should not automatically treat every SEZ-related entity or transaction as exempt.
Which Transactions and Documents Require an e-Invoice?
| Transaction / document | e-Invoice treatment |
|---|---|
| B2B taxable invoice | Yes, where the supplier is covered by the mandate |
| Export invoice | Yes, where the supplier is covered by the mandate |
| Debit note | Yes, where covered by the mandate |
| Credit note | Yes, where covered by the mandate |
| Deemed export | Covered where applicable under the notified e-Invoice rules |
| SEZ supply | Depends on the supplier and nature of supply; check the applicable e-Invoice rule |
| B2C invoice | No |
| Bill of Supply | No |
| Exempt supply | Not reported as an e-Invoice |
| Import invoice issued by foreign supplier | Not generated by the foreign supplier through India’s e-Invoice system |
Is e-Invoicing Mandatory for B2C Transactions?
No. Under the current GST e-Invoicing framework, B2C invoices are not required to be reported to an Invoice Registration Portal. The mandate primarily applies to specified B2B invoices and other notified documents issued by eligible taxpayers.
Is e-Invoicing Applicable to a Bill of Supply?
No. A Bill of Supply is not one of the documents reported to the IRP for e-Invoicing. Businesses issuing a Bill of Supply should follow the GST requirements applicable to that document instead of trying to generate an IRN for it.
GST e-Invoice Format and Schema (INV-01)
The GST e-Invoice system uses a standard schema commonly referred to as INV-01. The invoice itself may still be designed in a business-friendly layout, but the data reported to the IRP must follow the prescribed schema.
Typical e-Invoice data includes:
- Supplier GSTIN and legal/trade details
- Recipient GSTIN and address details
- Invoice number, date and document type
- Place of supply
- Item description, quantity and value
- HSN or SAC
- Taxable value and GST components
- Total invoice value
- Export or reverse-charge details where applicable
- Transport/e-Way Bill information where relevant
Businesses using billing software normally do not need to manually build JSON for every invoice; compatible software can prepare the structured data from the invoice already created in the system.
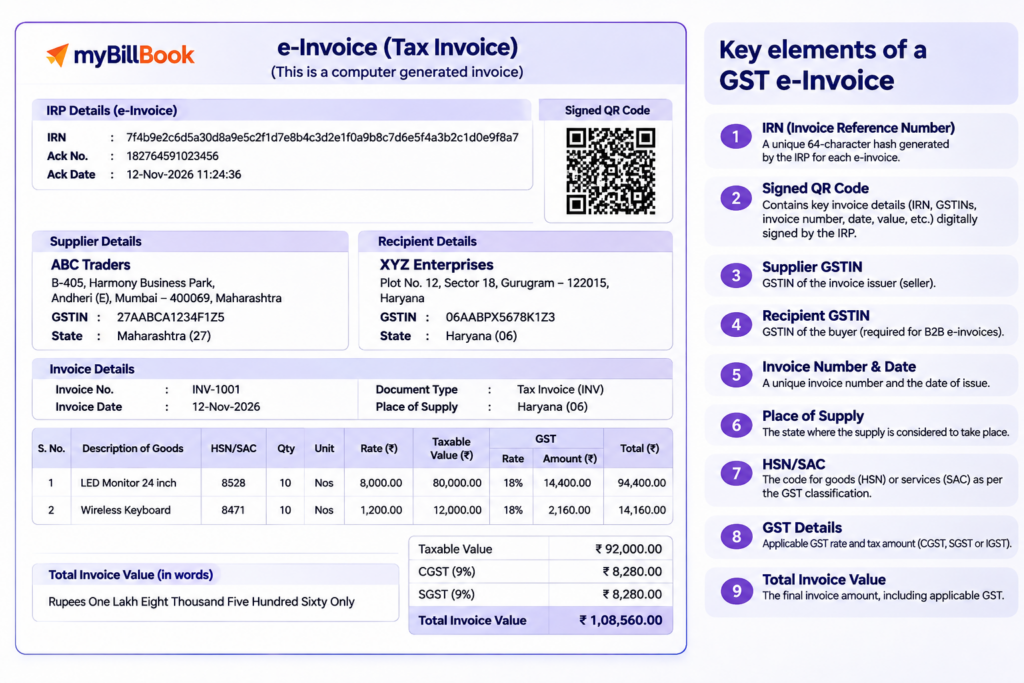
GST e-Invoice Sample: What Should You Check?
A valid e-Invoice should contain the normal GST invoice information plus the e-Invoice registration details returned by the IRP. When reviewing an e-Invoice sample, check for the following:
- Invoice number and date
- Supplier GSTIN
- Recipient GSTIN
- Place of supply
- HSN/SAC and taxable values
- GST amount split
- Invoice Reference Number (IRN)
- Signed QR code
What Is an Invoice Reference Number (IRN)?
The Invoice Reference Number is the unique reference generated for a successfully registered e-Invoice. It helps identify the invoice in the e-Invoice system and is returned by the IRP after validation. Read the detailed guide to IRN under GST.
What Is the QR Code on an e-Invoice?
The IRP returns a digitally signed QR code containing key invoice information. The QR code helps users and tax authorities verify important invoice details and confirm that the invoice was registered through the e-Invoice system.
How to Verify an e-Invoice
An e-Invoice can be checked using the verification facilities provided in the GST e-Invoice ecosystem. Verification generally uses the QR code, IRN or invoice details to confirm that the invoice was registered and that key details match the IRP record.
How to Generate an e-Invoice
Method 1: Through an authorised Invoice Registration Portal
- Create the invoice in your accounting or billing system.
- Prepare the required invoice data in the prescribed format.
- Log in to an authorised IRP or use its supported upload utility.
- Upload or enter the invoice details.
- Submit the invoice for validation.
- Download or receive the registered invoice data with IRN and signed QR code.
Method 2: Through integrated billing or accounting software
Compatible software can send invoice data to the IRP from the billing workflow, receive the IRN and QR code, and update the invoice without repeated manual entry. For myBillBook users, see the dedicated e-Invoicing feature page.
What Is the Time Limit for Generating or Reporting an e-Invoice?
From 1 April 2025, taxpayers with aggregate annual turnover of ₹10 crore or more must report applicable invoices, credit notes and debit notes to the IRP within 30 days from the document date. The IRP restricts IRN generation where a document covered by this rule is reported after the permitted 30-day window.
This reporting restriction previously applied to taxpayers with AATO of ₹100 crore or more and was extended to the ₹10 crore-and-above category from April 2025. Businesses should check the latest official advisory before relying on a reporting deadline.
e-Invoice vs Normal GST Tax Invoice
| Point | Normal GST tax invoice | GST e-Invoice |
|---|---|---|
| Created by | Supplier | Supplier |
| Reported to IRP | Not necessarily | Yes, when e-Invoice rules apply |
| IRN | Not required | Required for a registered e-Invoice |
| Signed QR code from IRP | No | Yes |
| Standard electronic reporting schema | Not required merely for issuing a normal invoice | Required for IRP reporting |
An e-Invoice is still a tax invoice created by the supplier; the key difference is that its prescribed data is electronically registered with the IRP.
e-Invoice vs e-Way Bill
| Point | e-Invoice | e-Way Bill |
|---|---|---|
| Main purpose | Electronic registration of specified invoice documents | Compliance document for movement of goods where applicable |
| Key identifier | IRN | e-Way Bill Number |
| Trigger | e-Invoice applicability rules | e-Way Bill rules for movement of goods |
| Integration | Invoice data can support connected GST/e-Way Bill workflows | May reuse relevant invoice details |
For the operational workflow, see the e-Way Bill feature.
Benefits of e-Invoicing Under GST
- Standardised invoice reporting: Businesses report invoice information in a common structured format.
- Less repeated data entry: Registered invoice data can be reused across connected GST processes.
- Better data consistency: Validation helps identify incomplete or structurally incorrect invoice data before registration.
- Improved traceability: IRN and QR-code-based registration create a stronger audit trail for notified transactions.
- Smoother integration: Billing and accounting software can connect e-Invoice generation with invoice creation and related compliance workflows.
Common e-Invoice Mistakes to Avoid
- Assuming every GST invoice automatically needs an IRN
- Using only current-year turnover instead of checking the applicable turnover history
- Treating B2C invoices or Bills of Supply as documents that must be reported to the IRP
- Reporting incorrect GSTIN, invoice number, tax values or place-of-supply details
- Missing the 30-day reporting restriction where the taxpayer has AATO of ₹10 crore or more
- Confusing an e-Invoice with an e-Way Bill
- Assuming portal enablement alone proves legal applicability
You can also use our GST invoice validation checklist before issuing invoices.
Frequently Asked Questions
Can a business voluntarily generate e-Invoices if turnover is below the mandatory threshold?
Businesses below the notified threshold should check the current GST/IRP rules before attempting voluntary e-Invoicing. Eligibility, enablement and legal applicability are not always the same thing.
Can the buyer generate an e-Invoice on behalf of the supplier?
The e-Invoice obligation is linked to the supplier issuing the relevant document. The supplier’s GSTIN, applicability and reporting workflow determine whether an IRN must be generated.
Is e-Invoicing applicable to services?
Yes. The mandate can apply to eligible suppliers of services as well as goods, unless the supplier falls within a notified exemption.
Can an e-Invoice be amended after IRN generation?
The IRP does not function as a general invoice-editing system. If an error is found after registration, the business must follow the permitted cancellation or GST amendment process depending on the nature and timing of the correction.
Is a physical signature required on an e-Invoice?
The e-Invoice system returns digitally signed registration data and a signed QR code. Businesses should ensure the final invoice complies with the signature requirements applicable to their invoicing method and GST process.
Official references used for rule verification: GST e-Invoice mandate and authorised IRP advisories, including the ₹5 crore applicability threshold and the 30-day reporting restriction applicable to taxpayers with AATO of ₹10 crore or more from 1 April 2025.